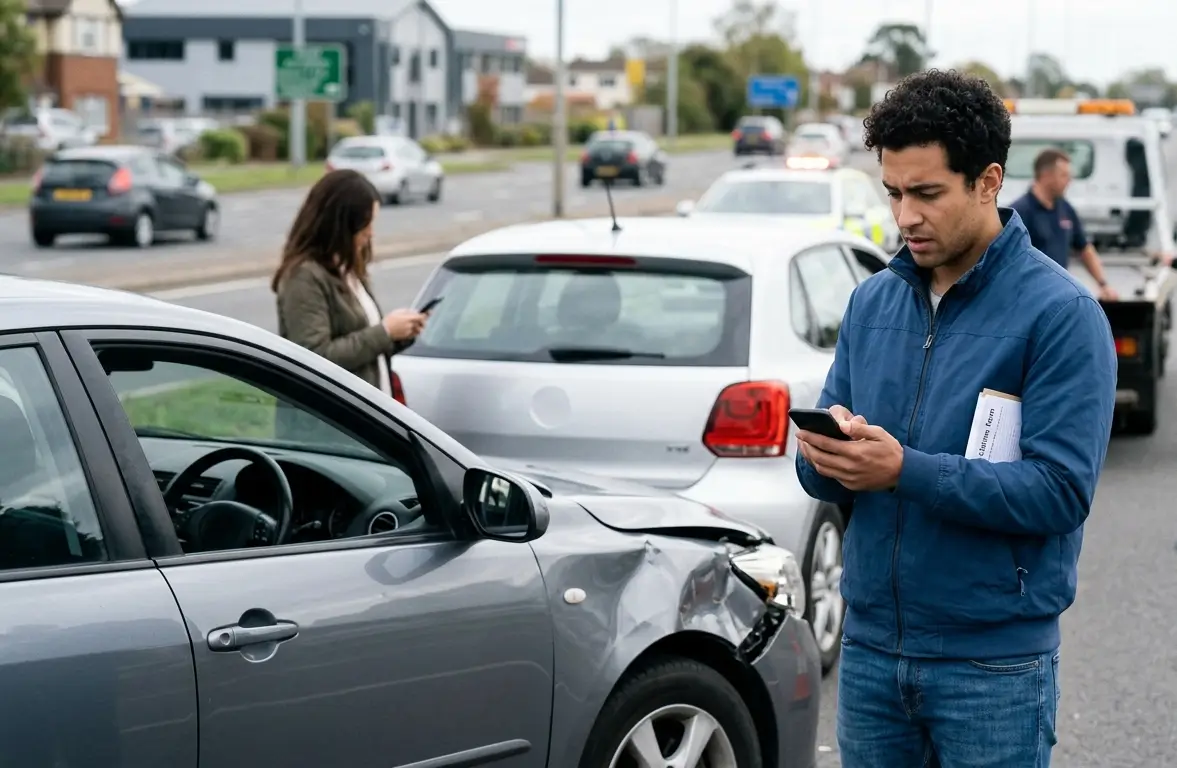
A car accident can turn an ordinary day into a stressful experience. You may have to deal with vehicle damage, injuries, hospital visits, police questions, and insurance paperwork. During this time, it is easy to miss an important step that could affect your claim.
The good news is that you can take practical steps to protect your position. You don’t need to understand every insurance or legal rule. Safety must come first, relevant information must be gathered, the incident must be appropriately reported, and accurate documentation must be kept. Whether another vehicle hit your car or you suffered an injury in a road accident, your next actions matter. Here is what you should do to protect your car accident claim in India.
1. Put Safety Before Your Car Accident Claim
Your health and safety come first. Do not start arguing about who caused the accident while someone needs medical attention. Move to a safe place if you can do so without putting yourself or others at risk. Turn on your hazard lights and warn approaching traffic when it is safe. Call emergency services if anyone has suffered a serious injury. In India, you can ring 112 for help in an emergency. Even if your injury looks small, seek medical help if you experience pain, swelling, or other unusual symptoms.
Keep Your Medical Records Safe
Visit a hospital or doctor and explain how the accident happened. Keep prescriptions, medical reports, test results, hospital bills, and payment receipts. These records can help explain the nature of your injuries and the treatment you received. They may also support an injury compensation claim, depending on the circumstances and applicable law. Do not ignore follow-up appointments. Your health should guide your treatment decisions, not your expectations about compensation.
2. Collect Evidence at the Accident Scene
Evidence can help establish what happened. It may also help your insurer, the police, or a claims tribunal understand the incident. If the situation is safe, collect useful information before vehicles leave the scene or witnesses disappear.
a) Take Clear Photos and Videos
Take a video of the accident scene with your phone. Take pictures from different angles and capture details that may help explain how the collision occurred.
Try to photograph:
- Damage to all vehicles involved.
- Vehicle registration numbers.
- The positions of the vehicles, if they remain in place safely.
- Road signs, traffic signals, skid marks, and visible road conditions.
- Any visible injuries, if appropriate and with respect for privacy.
Keep the original photos and videos. Avoid editing them in a way that changes the facts. Never put yourself in danger or block traffic just to collect evidence.
b) Collect Details From Other Drivers and Witnesses
Write down the other driver’s name, contact details, license plate number, and insurance information. If anyone saw what happened, ask for their name and phone number as well. Try to stay calm and avoid arguing or accusing anyone. Keeping things peaceful makes exchanging information much easier. Finally, check if any nearby businesses, buildings, or parked cars have security cameras. Your lawyer or the police can use that information to request the footage before it gets wiped.
3. Inform the Police When Required
You should not assume that every minor accident follows the same police procedure. The circumstances, injuries, damage, and applicable rules can affect what you need to do. If someone suffers an injury or dies, a serious dispute arises, or a driver leaves the scene, contact the police promptly. Follow their instructions and provide an honest account of what happened.
Keep a Copy of the FIR or Other Police Records
Ask the police how to get a copy of the FIR once it is registered. Be sure to save all receipts, complaint copies, and accident records. Keep in mind that while an FIR indicates that the collision was reported, it does not prove every detail or ensure that you will be compensated. To obtain further information, the police will conduct additional investigations.
Always be honest about what transpired. Never sign a statement you know is untrue, fabricate information, or overstate injuries or damage. For injury or death cases, legal procedures may involve additional documents and a Motor Accident Claims Tribunal (MACT). A lawyer experienced in motor accident claims can explain the process for your particular case.
4. Notify Your Insurance Company Promptly
Notify your insurance company as soon as possible after the accident. Use the website, mobile app, helpline, or other contact details in your policy. Explain what happened and ask the company to register your claim. Record the claim number and the date of your notification. Also, note any instructions the claims team gives you. Don’t expect your insurance company to get the information from the police or another motorist.
Understand Your Insurance Coverage
Your policy determines what losses it may cover. Third-party liability insurance generally covers your legal liability for injury or damage to others. It does not normally pay for damage to your own car. A comprehensive or package policy may cover damage to your own vehicle, subject to the policy terms, exclusions, deductibles, and other conditions.
Read your policy carefully. You can also review the IRDAI motor insurance guidance for a basic explanation of motor insurance and common claim documents.
Ask Before Repairing Your Car
Do not rush to repair the vehicle before you understand your insurer’s inspection and car accident claim process. The insurer may need to inspect the damage or arrange a survey. Ask whether you should use a network garage, submit an estimate, or wait for approval. Keep the repair estimate, invoices, payment receipts, and any inspection report. If you need to move the vehicle for safety concerns, take pictures if possible beforehand and make a record of any towing costs.
5. Organise Every Document Related to Your Claim
Missing paperwork can delay things. Make a folder on your phone or computer and print hard copies if required. The exact documents depend on your policy and the type of claim. Commonly requested items may include:
| Document | Why it may help |
| Motor insurance policy | Shows your insurance coverage and policy details |
| Registration Certificate (RC) | Identifies the vehicle and registered owner |
| Driving licence | Provides details of the driver |
| FIR or police records, if applicable | Records the reported accident and police action |
| Accident photos and videos | Shows visible damage and scene details |
| Repair estimate and bills | Supports the cost of vehicle repairs |
| Medical records and bills | Documents injuries and treatment expenses |
| Claim form and insurer correspondence | Records the claim details and communication |
Your insurer may request additional documents. Follow its checklist and ask for clarification if you do not understand a requirement. Keep digital backups and avoid sending original documents unless the insurer specifically requires them through a proper process.
6. Be Careful About Statements and Settlement Offers
Provide accurate information regarding the crash when speaking with the other driver or an insurance agent. Admitting that you don’t know anything is preferable to speculating. Never acknowledge your mistakes to diffuse a heated discussion. Stay true to the facts, don’t invent anything, and let the police and insurance companies use the evidence to determine who was at fault.
Read Before You Sign
Never sign a document you don’t understand or a blank form. Before agreeing, thoroughly read any statement, settlement offer, or discharge instrument. Don’t accept a hasty payment without knowing what it covers if you think the other person caused the accident. Depending on the conditions of the settlement and the relevant legislation, it may limit your ability to pursue additional compensation. Before agreeing to a final settlement, speak with an experienced attorney if there are significant losses, serious injuries, contested liability, or a potential compensation claim.
7. Understand Difference Between Car Insurance Claim and Compensation
People often use the term “car accident claim” for different situations. Understanding the difference can help you take the correct next step. An own-damage insurance claim seeks payment for damage to your vehicle under a policy that covers that loss. The insurer will assess the car accident claim according to the policy terms.
Legal responsibility for harm, death, or property damage inflicted upon another individual is the subject of a third-party insurance claim. If you are hurt in an accident, you may be able to sue the person who caused it, depending on the relevant circumstances and procedure.
In India, the Motor Accident Claims Tribunal can hear certain claims involving death, bodily injury, and third-party property damage arising from motor accidents. You can read the relevant provisions through the official India Code website.
The right route depends on what happened. A car accident claim for repairing your car is not the same as a claim for personal injury compensation.
What If the Insurance Company Delays or Rejects Your Claim?
First, request a formal explanation of the rejection or delay from the insurer. Examine the policy’s terms to see whether you need to provide any missing paperwork or provide clarification on any points. If you disagree with the decision, raise a formal complaint through the insurer’s grievance redressal process. Keep a copy of your complaint and supporting records.
You can also review the IRDAI grievance redressal guidance for information about escalation options. The appropriate route will depend on the issue and the insurer’s response. For a disputed injury compensation claim, consider getting independent legal advice. Do not assume that an insurer’s decision automatically settles every legal issue connected with an accident.
Conclusion
A few practical methods to protect your car accident claim. Always place safety first, get medical attention when necessary, gather evidence, make a formal report of the accident, and inform your insurer without undue delay. Keep your documents organised and read every form before signing it. Avoid false statements and do not accept a final settlement until you understand its terms.
Most importantly, remember that every accident has different facts. Your policy, the available evidence, and the applicable law will affect the outcome. If the accident involves serious injuries, a death, disputed fault, or a large financial loss, seek qualified legal advice. A careful approach will help you understand your options and present your claim more clearly.